
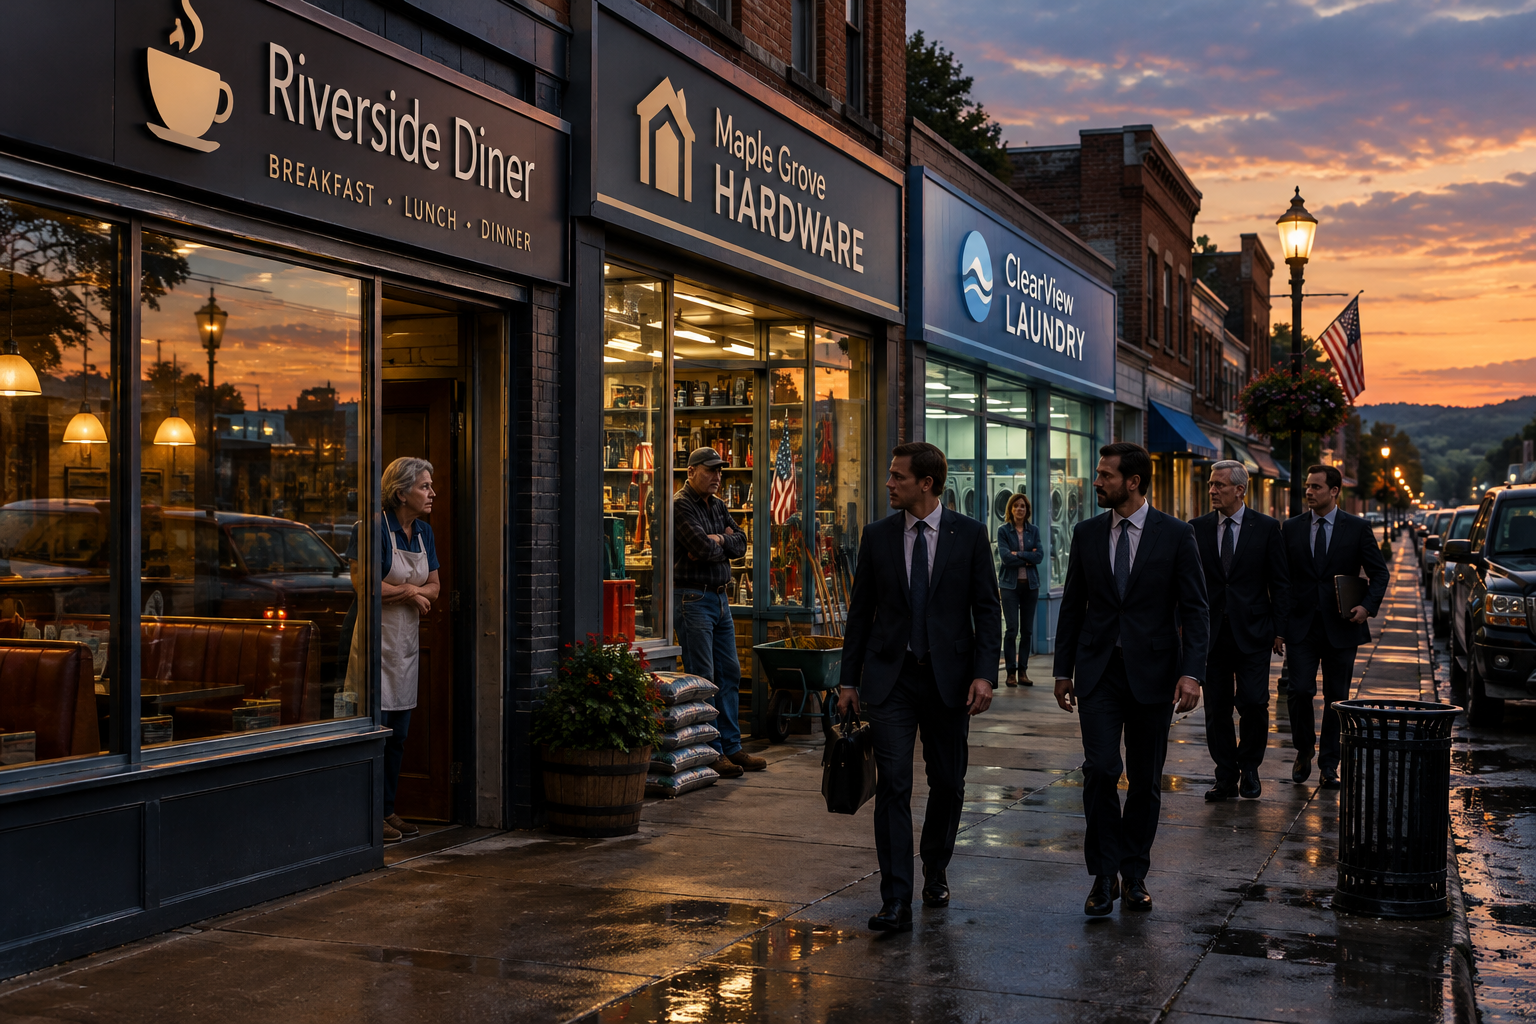
Private equity used to feel distant from the everyday economy. For many people, it belonged to the world of boardrooms, billion dollar funds, and Wall Street dealmaking. Today, that is no longer true. Private equity firms are increasingly active in the kinds of companies people visit every week, including dental offices, HVAC contractors, auto repair shops, veterinary clinics, home healthcare agencies, restaurants, and regional retail chains.
This shift matters because Main Street businesses sit at the center of local life. They provide jobs, deliver essential services, and often shape the character of a community. As private equity expands into these sectors, it is changing how small and mid-sized businesses are bought, financed, managed, and grown. The effects can be positive, negative, or mixed, depending on the strategy, the industry, and the time horizon involved.
The new ownership wave in local business
Main Street businesses have become attractive acquisition targets for a simple reason. Many of them operate in large, fragmented industries with thousands of independent owners. From a private equity perspective, fragmentation creates opportunity. A firm can buy one company, add more through acquisitions, improve operations, and then sell the larger combined platform at a higher valuation.
This model is often called a roll-up or buy-and-build strategy. It has become especially common in sectors where demand is recurring, customer relationships are sticky, and the service cannot easily be outsourced or digitized away. Think of accounting firms, urgent care centers, roofing companies, pest control businesses, and physical therapy clinics. These are practical, local, labor-intensive services that people and businesses continue to need regardless of broader economic trends.
Several structural factors have accelerated this ownership wave. One is demographics. Many small business owners are nearing retirement age and need succession plans. Family members may not want to take over, and strategic buyers may be limited. Private equity-backed buyers often arrive with cash, speed, and a clear acquisition process.
Another factor is the search for returns. As competition for large corporate deals has intensified, some investors have moved down market into the lower middle market, where smaller companies can still be bought at relatively more attractive prices. In addition, low interest rate periods over the past decade made it easier to finance acquisitions with debt, which has long been a core tool in private equity transactions.
Technology and data have also helped. Businesses once considered too small or too localized to scale can now be managed through centralized software, shared services, digital marketing, and standardized reporting. A dental clinic with one office may look like a local practice. A network of fifty offices using common scheduling systems, procurement contracts, and billing processes looks more like an investable platform.
Why private equity sees value in Main Street sectors
Private equity firms are not buying local businesses at random. They are targeting sectors with characteristics that fit their investment model. Understanding those characteristics helps explain why so many familiar businesses have become part of larger investment strategies.
Recurring or resilient demand
Many Main Street sectors offer services people need on an ongoing basis. Pets need care. Homes need repairs. Teeth need cleaning. Vehicles need maintenance. Aging populations need more health and support services. This kind of recurring demand can create stable revenue and reduce volatility.
Essential services are especially attractive during uncertain economic periods. Consumers may delay a luxury purchase, but they are less likely to ignore a broken air conditioner in summer or a plumbing leak. That resilience can support debt financing and make cash flows more predictable.
Fragmented competition
Private equity thrives where there are many small operators and no dominant national player. In fragmented industries, a buyer can acquire businesses at lower multiples than those assigned to larger, more sophisticated companies. By combining them, the buyer hopes to create scale and eventually earn a higher exit valuation.
The logic is financial and operational. Scale can improve purchasing power, spread fixed costs, strengthen branding, and make recruitment easier. It can also create more professional management structures than a founder-led business may have had.
Operational inefficiencies
Many owner-operated businesses perform well but lack formal systems. They may have weak reporting, inconsistent pricing, limited marketing analytics, and outdated technology. Private equity firms often see this as upside. By introducing dashboards, standard operating procedures, centralized back-office functions, and performance incentives, they aim to lift margins and increase enterprise value.
In some cases, these improvements are real and substantial. A local services company might reduce scheduling gaps, improve inventory management, or negotiate better supplier terms. In other cases, the push for efficiency can become overly aggressive and create strain for workers and customers.
Succession gaps
For many founders, selling to a private equity-backed platform is not just about price. It is also about continuity. The buyer may preserve the brand, keep key managers in place, and offer the seller a chance to retain equity in the larger combined company. That can be appealing compared with shutting down, selling to a competitor, or handing the business to an unprepared successor.
How the private equity playbook works on Main Street
Although every deal is different, the private equity approach to local businesses often follows a recognizable pattern. First, a firm identifies a sector where scale can be created. Then it acquires a strong initial company, sometimes called a platform investment. After that, it adds smaller businesses, often called add-ons, to expand geography, services, or customer base.
Once a platform is established, the owner may centralize accounting, human resources, procurement, and marketing. It may implement common software systems, standardize pricing, and create management reporting across all locations. The goal is to make the combined business more efficient, more measurable, and more valuable to a future buyer.
Debt often plays a role. In a classic leveraged buyout, borrowed money is used to finance part of the acquisition. The acquired business then helps repay that debt through its cash flow. This can magnify returns if performance improves, but it can also increase pressure on the company if conditions worsen. The use of leveraged finance has been widely discussed by policymakers because leverage can amplify both gains and risks.
Private equity firms also usually operate on a finite timeline. They are not buying to hold forever. Many funds aim to sell within three to seven years, though timelines vary. That matters because a business managed for a medium-term exit may make different choices than a family owner planning to pass the company to the next generation.
Industries seeing the biggest impact
Not all Main Street sectors are equally affected. Some have become especially active arenas for private equity investment because they combine local delivery with scalable economics.
Healthcare and health-adjacent services
Physician practices, dental groups, dermatology clinics, ophthalmology centers, urgent care operators, and behavioral health providers have all seen significant investment. These sectors benefit from steady demand, aging demographics, and opportunities to centralize administration. Billing, compliance, procurement, and site selection can all be managed at scale.
At the same time, healthcare raises difficult questions. If financial targets become too dominant, patient care, staffing levels, and treatment decisions may be affected. Researchers and policymakers have examined these issues closely. For context on market structure and incentives in healthcare, the economics of health care markets offers useful background.
Home and property services
HVAC, plumbing, electrical work, roofing, restoration, landscaping, and pest control are highly attractive to investors. These businesses often generate repeat demand, can expand through acquisitions, and benefit from centralized call centers, software, and technician scheduling. They also serve markets that remain local even when ownership becomes regional or national.
Consumers may notice changes through more polished branding, online booking, financing options, and broader service menus. They may also see higher prices if the new owner pushes average ticket values, upselling, or premium service packages.
Veterinary care and pet services
Pet ownership has risen, and owners are often willing to spend heavily on care. That has made veterinary clinics, specialty animal hospitals, and some pet service businesses attractive targets. Investors see a mix of emotional customer loyalty, recurring preventive care, and room for multi-site expansion.
Yet this sector also illustrates the tensions that can emerge. Veterinarians may face productivity pressures, and customers may encounter more standardized pricing and treatment recommendations. Some clinics gain better equipment and support. Others may feel less personal than they did under independent ownership.
Consumer and business services
Accounting firms, insurance brokerages, IT managed service providers, staffing companies, childcare operators, and education-related businesses have all drawn investor interest. These sectors often have recurring contracts, specialized expertise, and acquisition opportunities in local markets.
In many of these cases, private equity is not simply buying a store or office. It is buying a customer base, a reputation, a workforce, and a process that can be replicated across multiple markets.
The upside for owners, workers, and communities
It is easy to frame private equity as purely extractive, but that misses part of the story. In some cases, private equity ownership can bring meaningful benefits to Main Street businesses and the people connected to them.
Succession and liquidity for founders
For an owner who spent decades building a business, a sale can provide retirement security and a practical transition plan. Many founders are asset-rich but illiquid, with most of their wealth tied up in the company. Selling to a private equity-backed buyer can unlock value while preserving business continuity.
Some deals also allow owners to roll over a portion of their equity into the larger platform. If the combined company grows and is later sold at a higher value, the founder may benefit a second time. This can align incentives during the transition period.
Professionalization and growth
Small businesses often depend heavily on a single owner who handles sales, hiring, operations, and strategy all at once. That can limit growth and create bottlenecks. A better-capitalized owner may invest in management talent, technology, training, and systems that help the business scale.
For example, a regional plumbing business might gain a stronger dispatch platform, more efficient fleet management, improved recruiting, and better customer communication tools. A healthcare practice may gain compliance support, payer contracting expertise, and capital for new locations or equipment.
Employee opportunities
Although outcomes vary, larger organizations can sometimes offer clearer career paths, better training, stronger benefits, and more mobility than a standalone local business. A technician, office manager, or clinician may have more advancement opportunities inside a multi-site platform than in a single-location company.
Access to capital can also help a business survive and compete. In industries facing labor shortages, technology demands, or rising compliance requirements, outside investment may be the difference between stagnation and expansion.
The downside and the growing criticism
The concerns about private equity on Main Street are not theoretical. Critics argue that the model can create incentives that conflict with long-term service quality, workforce stability, and community accountability.
Debt burdens and short-term pressure
Leverage can make an acquisition possible, but it can also weigh down the business afterward. If too much debt is placed on the company, management may be forced to prioritize cash generation over reinvestment. That can mean deferred maintenance, reduced staffing, tighter inventory, or cuts to support functions.
In stable times, these tradeoffs may be manageable. In a downturn, they can become severe. A business that once had owner flexibility may suddenly face lender covenants, refinancing risk, and pressure to hit quarterly targets.
Price increases and aggressive monetization
One common criticism is that private equity-backed businesses may raise prices more aggressively than independent operators. This can happen through direct price increases, bundled services, financing programs, membership plans, or upselling tactics. In healthcare and veterinary settings, customers may feel especially vulnerable because they often lack pricing clarity and are making decisions under stress.
Higher prices are not always unjustified. Better technology, expanded hours, and improved facilities cost money. But when price increases outpace service improvements, public frustration tends to follow.
Workforce strain
Labor is one of the largest costs in many Main Street sectors, so it often becomes a focus for efficiency efforts. That can lead to tighter staffing models, more productivity monitoring, and pressure to standardize work. Employees may experience less autonomy and a more corporate culture than they did under a founder-owner.
In service businesses, that matters because quality often depends on people, not just process. A clinic, contractor, or repair shop can only optimize so far before morale, retention, and customer experience begin to suffer.
Loss of local identity
Main Street businesses often succeed because they are deeply embedded in their communities. They know local customers, sponsor neighborhood events, and make decisions based on relationships as well as margins. As ownership becomes more distant, those community ties can weaken.
The storefront may look the same, and the brand may remain, but the decision-making center may shift elsewhere. Policies on pricing, staffing, procurement, and customer service may be set by a regional office or investment committee rather than by someone who lives in the area.
What changes customers are most likely to notice
For customers, private equity ownership is often invisible at first. The business may keep its name, location, and familiar staff. Over time, however, several changes may become noticeable.
More polished operations
Customers may benefit from easier scheduling, faster response times, online payment options, text reminders, broader service hours, and more consistent communication. These are often real improvements that come from better systems and capital investment.
Standardized sales processes
Customers may also encounter more structured sales scripts, financing offers, membership plans, and service bundles. In home services, technicians may be trained to present tiered options. In healthcare or veterinary settings, customers may receive more formal treatment plans and pricing packages.
Brand expansion
A once-local company may suddenly advertise more aggressively, enter nearby markets, or acquire competitors. This can create convenience and broader availability, but it can also reduce local competition over time.
Regulation, transparency, and public scrutiny
As private equity has expanded into essential local sectors, regulators and researchers have paid closer attention. The key policy questions center on market concentration, pricing, labor practices, quality of care, and financial risk.
In healthcare, scrutiny has been especially intense because ownership changes can affect both costs and outcomes. In housing-related and consumer service sectors, attention has focused more on consolidation, consumer pricing, and service access. Antitrust authorities, state attorneys general, labor advocates, and industry watchdogs are all part of the conversation.
Transparency remains a challenge. Customers may not know who owns the business they are dealing with, especially when local branding remains intact after an acquisition. Employees may not fully understand the financial structure or the timeline guiding management decisions. Greater disclosure around ownership and control could become more important as consolidation continues.
How independent businesses are responding
Not every Main Street business will sell to a private equity-backed buyer, and not every sector will consolidate at the same pace. Independent businesses still have meaningful strategic options.
Differentiation through trust and specialization
Local operators can compete by emphasizing deep expertise, continuity of relationships, and community reputation. In many service categories, customers still value trust more than scale. A business that is highly specialized or known for exceptional service may remain difficult to commoditize.
Selective modernization
Independent ownership does not require outdated operations. Many local businesses are adopting better software, digital marketing, customer communications, and financial reporting without giving up control. In some cases, this allows them to capture many of the operational benefits associated with larger platforms while preserving local culture.
Alternative succession paths
Founders considering retirement may explore employee ownership, family transition, sale to a strategic operator, or recapitalization with minority investors. Private equity is one path, not the only one. The right choice depends on goals related to price, legacy, employee welfare, and long-term business direction.
What this means for the future of Main Street
The growing role of private equity in local business is part of a broader shift in the American economy. Industries once dominated by small independent firms are becoming more institutionalized. Capital, data, and management systems are moving into places that used to run mainly on owner intuition and local relationships.
This does not guarantee a single outcome. In some communities, private equity ownership will preserve businesses that might otherwise close, create jobs, and improve service quality. In others, it will contribute to higher prices, thinner staffing, and a loss of local accountability. Often, the reality will be somewhere in between.
The most important question is not whether private equity is present on Main Street. It already is. The more useful question is how ownership incentives are shaping the businesses people rely on every day. When financial discipline is balanced with operational investment, employee support, and customer value, the results can be constructive. When debt, speed, and exit timing dominate everything else, the costs can spread far beyond investors.
Main Street has always evolved with broader economic forces. Today, one of the strongest forces reshaping it is private equity. Owners, workers, customers, and policymakers all have a stake in how that story unfolds. The businesses may still look local from the sidewalk, but increasingly, the logic guiding them is being written in investment memos, acquisition models, and portfolio reviews. Understanding that shift is essential for anyone trying to make sense of the future of local commerce.