
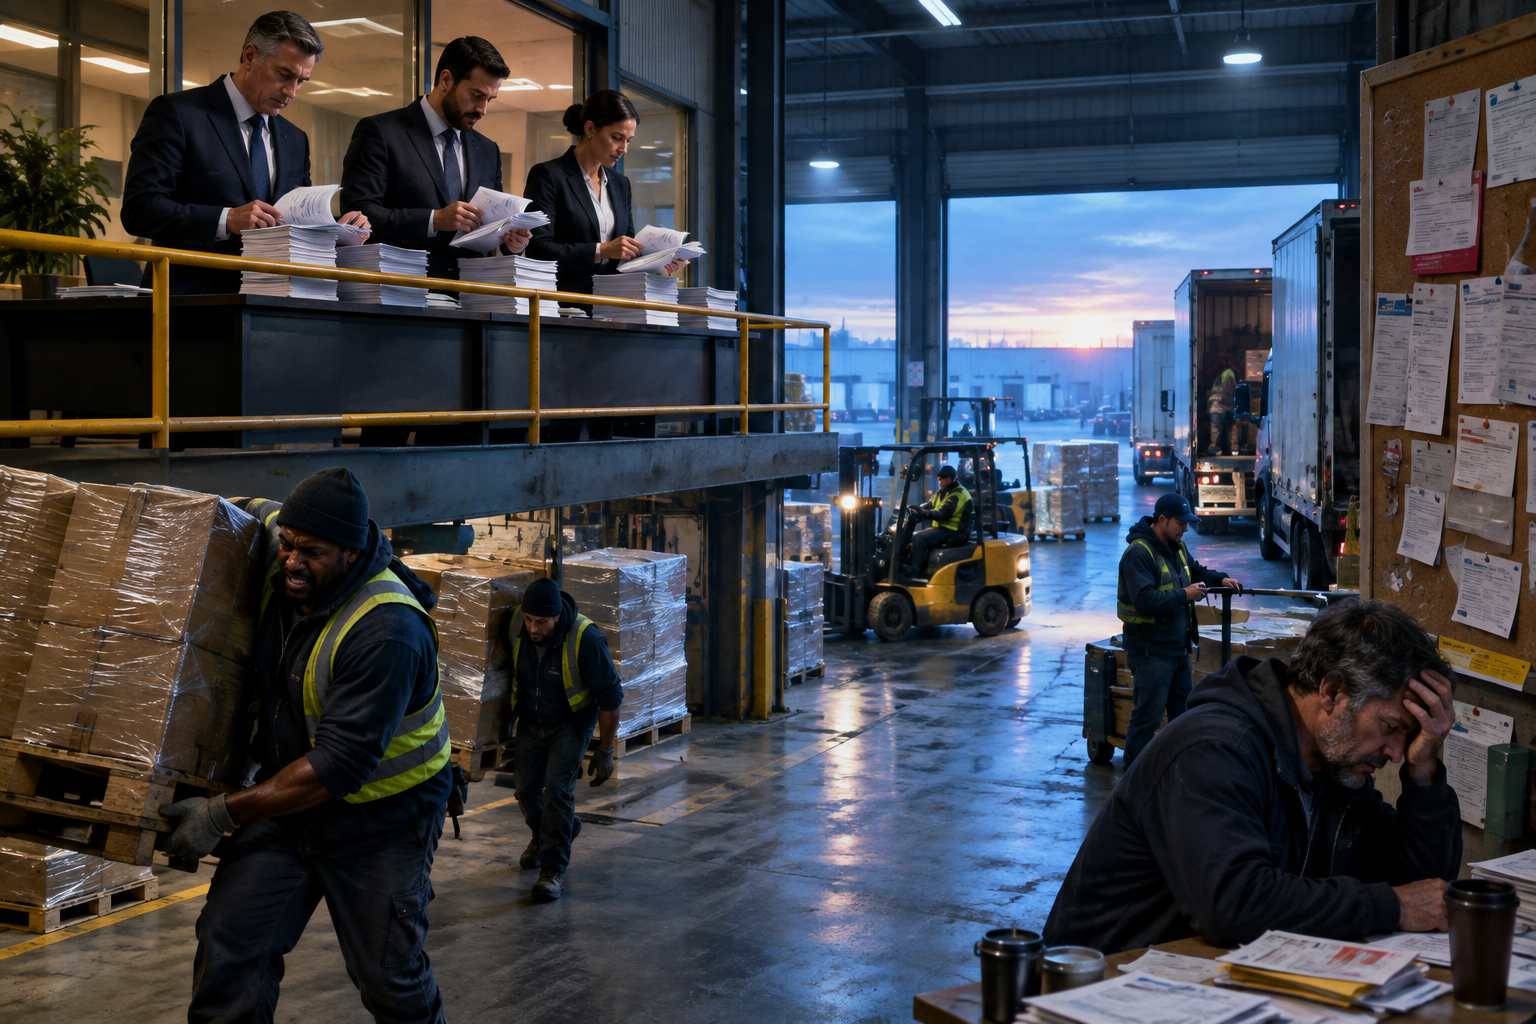
Corporate profits sit at the center of one of the biggest arguments in modern economics. Supporters see strong profits as evidence of healthy businesses, productive investment, and a dynamic economy that can fund innovation, jobs, and retirement savings. Critics see something else: rising prices, weaker bargaining power for workers, concentrated market power, and a larger share of national income flowing to owners of capital rather than to households trying to keep up with everyday costs.
The truth is more complicated than either slogan suggests. Profits can help push an economy forward, but they can also become a sign that the gains from growth are being captured unevenly. To understand whether corporate profits are lifting the broader economy or squeezing everyone else, it helps to look at what profits actually do, how they are generated, and who ultimately benefits when they rise.
Why profits matter beyond the boardroom
Profit is not just a reward for shareholders. In a market economy, profit is also a signal. It tells firms where demand is strong, where resources may be used more efficiently, and where investment might produce the highest return. When a company earns sustainable profits by making better products, lowering costs through innovation, or serving customers more effectively, those profits can guide capital toward productive uses.
This is one reason economists often treat profits as a necessary part of growth. Businesses need retained earnings and access to capital to expand production, hire workers, build factories, improve software, and fund research. In that sense, profits are not merely money extracted from the economy. They can be fuel for future output.
At the same time, not all profits are created in the same way. A company that earns high profits because it discovered a breakthrough treatment or developed a more efficient manufacturing process is different from a company that earns high profits because it faces little competition, can raise prices with minimal resistance, or uses its scale to pressure suppliers and workers. The source of profits matters just as much as the size of profits.
That distinction is at the heart of the debate. If profits mostly reflect productivity and innovation, they can support broad prosperity. If they mostly reflect pricing power and concentration, they may signal a transfer of income away from consumers and labor.
How corporate profits can drive economic growth
There are several ways in which strong corporate profits can genuinely support the economy.
Profits finance business investment
One of the clearest benefits of profit is that it helps firms invest without relying entirely on borrowing. Retained earnings can fund equipment upgrades, logistics improvements, new stores, new data centers, and research programs. These investments can raise productivity, which is the foundation of long run wage growth and rising living standards.
For example, a manufacturer that earns strong profits may invest in automation that reduces waste and speeds up production. A software company may use profits to build better tools that improve efficiency for thousands of business customers. A retailer may improve inventory systems, reducing shortages and lowering operating costs. In each case, profits are not simply cash hoarded at the top. They can become the source of future economic capacity.
Profits support entrepreneurship and risk-taking
Without the possibility of profit, fewer investors would back uncertain ventures. New drugs, clean energy technologies, advanced chips, and novel business models often require years of spending before any payoff appears. The expectation of profit is what makes many of those bets possible in the first place.
This is especially important in sectors where failure rates are high. Venture capital, private investment, and public equity markets all depend on the idea that a few big winners can offset many losses. If profit opportunities disappear, capital may become more cautious, and the pace of experimentation can slow.
Profits can strengthen retirement systems and household wealth
Many households benefit from corporate profits indirectly through pension funds, retirement accounts, and index funds. When profitable firms grow and pay dividends or increase in value, those gains can flow to workers saving for retirement. In economies where public pensions are limited, private asset ownership becomes an important channel through which profits benefit ordinary households.
This does not mean gains are evenly distributed. Wealthier households own more financial assets, so they capture a larger share of the upside. Still, it is too simple to say that only executives and large investors benefit from rising profits. Millions of people have some exposure through retirement plans and mutual funds.
Profits can improve resilience during downturns
Highly profitable firms often have stronger balance sheets. That can matter during recessions, supply chain disruptions, or sudden changes in demand. Companies with healthy margins may be better able to avoid layoffs, continue capital spending, or absorb temporary cost increases without collapsing.
In that sense, profits can act as a buffer. An economy filled with fragile firms operating on razor-thin margins may look consumer-friendly in the short term, but it can be less stable when conditions worsen.
When profits become a sign of pressure on households
The case against rising corporate profits is not that profits are inherently bad. It is that in some periods and sectors, profits rise for reasons that impose real costs on workers, consumers, and smaller businesses.
Higher prices can lift profits faster than wages
One of the most common concerns is that firms raise prices more quickly than their costs increase, widening margins while households struggle with inflation. During periods of supply disruption or strong demand, companies may find it easier to pass through price increases and even go beyond cost recovery.
If wages do not keep pace, consumers lose purchasing power. Families spend more on food, housing-related goods, transportation, and services, while businesses report strong earnings. This is one reason the public often views profit growth skeptically during inflationary periods. People experience the economy through bills, not through earnings reports.
Research from institutions like the U.S. Bureau of Labor Statistics productivity program helps show why this matters. Over time, broad prosperity depends on productivity and compensation rising together. When prices and profits surge without a comparable increase in wages or output, the distributional tension becomes more visible.
Market concentration can create pricing power
Profits become more troubling when they are tied to weak competition. In concentrated industries, a small number of firms may be able to raise prices, limit choices, acquire rivals, or control key distribution channels. This does not require a formal monopoly. Even an oligopoly can produce an environment where firms face limited pressure to compete aggressively on price.
Examples are often debated in industries such as airlines, pharmaceuticals, meat processing, digital advertising, and parts of consumer goods. In these markets, scale can create efficiencies, but it can also create barriers that protect incumbents. If consumers have few alternatives, high profits may reflect power rather than superior performance.
The broader economic problem is that excess market power can reduce dynamism. New entrants struggle to gain traction. Suppliers face tougher terms. Workers have fewer employment options. Innovation may actually slow if dominant firms can maintain margins without taking meaningful risks.
Labor can be squeezed when bargaining power is weak
Another criticism is that profits rise partly because labor’s share of income has fallen in some sectors and periods. If workers lack bargaining power, companies may keep wage growth modest even as productivity improves or prices rise. That can boost margins while leaving employees with a smaller slice of the value they help create.
This issue is not only about hourly pay. It also includes scheduling practices, benefits, job security, subcontracting, and geographic concentration of employers. In local labor markets with few large employers, workers may have limited ability to negotiate better terms or switch jobs without relocating.
From a macroeconomic perspective, this matters because household spending drives a large share of economic activity. If profit growth comes at the expense of wage growth for a broad segment of workers, demand can become more fragile. The economy may then rely more heavily on debt or asset inflation to sustain consumption.
Small businesses often feel the squeeze too
The phrase “everyone else” does not just mean consumers and workers. It can also include smaller firms. Large corporations with strong margins may use their scale to secure better input prices, dominate advertising channels, negotiate favorable shipping rates, or absorb temporary losses that smaller competitors cannot survive.
In that environment, headline corporate profitability may coexist with a harsher reality for independent businesses. A local retailer, restaurant, supplier, or startup may face rising costs, limited financing, and intense pressure from giant firms that can operate with far more leverage over the market. The result can be an economy that looks healthy in aggregate while becoming less diverse and less competitive underneath.
The difference between productive profits and extractive profits
A useful way to think about the debate is to separate productive profits from extractive profits.
Productive profits
Productive profits generally come from creating more value. A company invents a better product, organizes work more efficiently, improves quality, or finds a way to deliver the same result with fewer resources. Customers willingly pay because they are getting something better, faster, safer, or cheaper. Competitors can respond by improving their own offerings, which spreads the gains through the economy.
These profits tend to support growth because they are linked to real improvements in output and capability. They often encourage imitation, investment, and diffusion of new technology.
Extractive profits
Extractive profits are different. They arise when firms capture value without creating much additional value. That can happen through monopoly power, regulatory capture, hidden fees, anti-competitive mergers, exploitative contract terms, or pricing strategies that take advantage of customer lock-in. It can also happen when firms use complexity to make comparison shopping difficult.
These profits may enrich shareholders in the short run, but they do less to expand the economy’s productive capacity. In some cases, they actively weaken it by reducing competition, discouraging entry, and shifting income away from households with a high propensity to spend.
The challenge for policymakers is that both types of profits can look similar in quarterly earnings. A high margin does not announce whether it came from innovation or from market power. That requires deeper analysis of industry structure, pricing behavior, investment patterns, and labor outcomes.
What recent economic trends suggest
In recent years, the profit debate has intensified because several trends have collided at once: inflation, supply chain disruption, rising interest rates, growing concentration in some industries, and public frustration over affordability.
During inflationary periods, many consumers notice that major companies continue to post strong earnings while household budgets tighten. This creates a natural suspicion that firms are using broad cost pressures as cover for larger price increases. Economists disagree over how large this effect is across the whole economy, but there is little doubt that some firms with strong brands or limited competition can protect or expand margins during turbulent times.
At the same time, not every increase in profit is evidence of abuse. Some firms genuinely navigated supply shocks better than others, improved operations, or benefited from shifts in consumer demand. Industries are heterogeneous. Energy, technology, consumer staples, healthcare, and industrials all operate under different cost structures and competitive pressures.
Another important trend is the rise of intangible capital. Modern firms often invest heavily in software, patents, data, logistics systems, and brand development. These assets can create winner-take-most dynamics, where a small number of firms achieve large scale at relatively low marginal cost. That can produce very high profits even without traditional factories or massive payroll growth.
This changes the political economy of profits. In older industrial models, profit growth often came with visible expansion in physical investment and employment. In digital and platform-heavy sectors, profit growth may be less labor-intensive and more concentrated, which can make it feel less connected to broad-based prosperity.
Why GDP growth alone does not settle the argument
Some argue that if the economy is growing, profits must be playing a positive role. But GDP growth alone cannot answer the distribution question. An economy can expand while gains flow disproportionately to a narrow group of firms and asset owners.
That is why economists also watch measures such as wage growth, labor force participation, productivity, business formation, market concentration, household debt burdens, and real purchasing power. Growth that depends heavily on pricing power and asset appreciation may look strong on paper while leaving many households feeling stuck.
For a broader framework, the International Monetary Fund’s discussion of competition and the economy is useful because it highlights how competitive markets help translate business success into wider social benefits. When competition weakens, profits may rise without delivering the same economy-wide payoff.
The role of policy in shaping whether profits help or hurt
Corporate profits do not exist in a vacuum. Tax policy, antitrust enforcement, labor law, trade rules, intellectual property protections, and financial regulation all influence how profits are generated and distributed.
Antitrust and competition policy
If policymakers want profits to reflect innovation rather than dominance, competition policy matters. Strong antitrust enforcement can limit anti-competitive mergers, challenge exclusionary practices, and preserve room for new entrants. The goal is not to punish success. It is to make sure success remains contestable.
Healthy competition tends to channel profits toward firms that serve customers best, not simply those that control the most bottlenecks. It also helps keep pressure on prices and encourages continuous improvement.
Labor market institutions
Whether workers share in economic gains depends partly on labor market rules and norms. Minimum wage laws, collective bargaining frameworks, overtime standards, noncompete restrictions, and worker classification rules all affect bargaining power. When labor markets are tight and workers have real options, profit growth is more likely to be accompanied by stronger wage growth.
This does not mean every rise in wages is costless. But an economy where workers consistently lose ground while profits climb can become politically unstable and economically unbalanced.
Tax policy and capital allocation
Tax rules also shape what firms do with profits. If the system strongly favors share buybacks over productive investment, companies may return more cash to shareholders instead of expanding capacity or funding long-term projects. If incentives support research, training, and capital formation, profits may be more likely to feed future growth.
Critics of high corporate profitability often point to buybacks as evidence that profits are enriching investors without helping the real economy. Defenders respond that returning excess capital can be efficient if firms lack attractive investment opportunities. Both views contain some truth. The key question is whether the corporate sector is broadly investing enough to support future productivity.
How households experience the profit economy
For most people, the profit debate is not theoretical. It shows up in grocery bills, rent, insurance premiums, internet service, prescription costs, and wages. A worker may hear that corporate earnings are strong and wonder why that strength has not translated into easier monthly finances. A small business owner may see large public companies thriving while their own margins shrink. A retiree with a pension or index fund may benefit from rising profits while also paying more for essentials.
That mixed experience is why the issue remains politically potent. The same person can benefit from profits as an investor and feel harmed by them as a consumer. The same economy can produce world-class firms and widespread financial stress at the same time.
This tension also explains why public trust can weaken even during periods of respectable aggregate growth. If the rewards of expansion are visible mainly in stock indices and executive compensation, many households will conclude that the system is tilted, regardless of what headline GDP says.
So are corporate profits driving growth or squeezing everyone else?
The most honest answer is that they can do both, and often at the same time. Corporate profits are essential to a functioning market economy. They reward innovation, attract capital, support investment, and can increase resilience. Without profits, businesses would have less reason and less ability to take risks, improve productivity, and build the tools that raise living standards over time.
But profits are not automatically a sign of healthy capitalism. When they rise because competition is weak, wages lag, or consumers have few alternatives, profits can become evidence of economic imbalance. In those cases, corporate success may reflect the ability to extract more from workers, customers, and smaller firms rather than the ability to create more value for society.
The real question is not whether profits are good or bad. It is whether the economy is structured so that profits mostly come from productive activity and are widely transmitted through wages, lower costs, better products, stronger investment, and broader opportunity. If that transmission works, profits can indeed drive the economy forward. If it breaks down, profits may still rise, but more people will feel squeezed.
In the end, a healthy economy needs profitable firms and fair distribution at the same time. Strong businesses matter. So do competitive markets, rising real wages, affordable essentials, and room for smaller players to thrive. The debate over corporate profits is really a debate over what kind of growth an economy is producing, who captures it, and whether success at the top is being converted into prosperity for the many rather than just the few.